Interchange is one of the key components of payment processing costs, but it is also one of the areas that can be difficult for business owners to understand. When a customer pays with a credit or debit card, the transaction involves several parties, including the cardholder’s bank, the business’s payment provider, and the card network. Interchange refers to the fee paid by the merchant’s bank or payment processor to the cardholder’s bank for processing the transaction. Understanding how interchange works can help businesses better understand their processing statements and the costs associated with accepting card payments.
Interchange rates are not always the same for every transaction. They can vary based on factors such as the type of card used, how the payment is accepted, the type of business, and the information provided during the transaction. For example, a card-present transaction at a physical location may have different interchange considerations than an online transaction where the card is not physically present. Businesses should understand that the rate associated with one transaction does not necessarily represent the cost of every payment they process.
The type of card used can also influence interchange costs. Credit cards, debit cards, rewards cards, commercial cards, and other card categories can have different interchange rates. Certain cards may carry higher costs because of the benefits or programs associated with them. As customers use a variety of payment cards, a business’s overall processing costs can reflect the mix of transactions it receives rather than one fixed interchange rate.
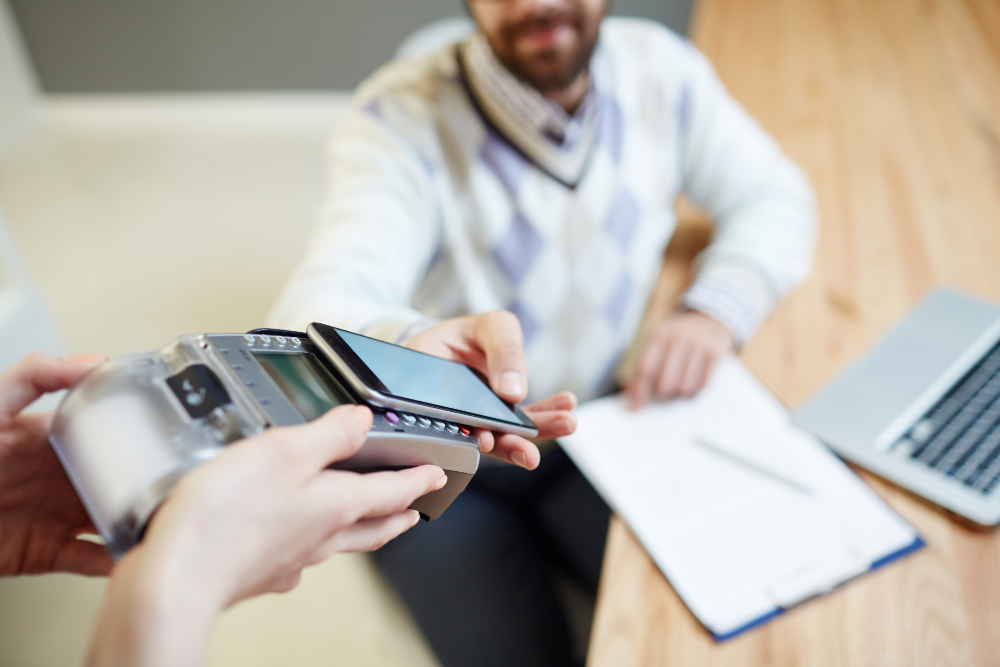
How a transaction is entered can be equally important. Card-present transactions, contactless payments, online purchases, and manually keyed transactions may be treated differently within the payment system. Providing accurate transaction information and using appropriate payment technology can help ensure that transactions qualify for the applicable pricing category. Businesses that frequently accept card-not-present or manually entered payments should pay particular attention to how those transactions affect their overall processing costs.
Interchange is also different from the other fees that may appear on a payment processing statement. A processor may charge additional costs for its services, technology, account management, payment gateways, equipment, or other features. Card networks may also have their own assessment fees and other charges. As a result, the total amount a business pays to process a transaction is generally made up of more than just the interchange component. Looking at the full pricing structure is important when evaluating the actual cost of a payment solution.
Businesses should also be cautious about comparing providers based only on a single advertised processing rate. A lower quoted rate does not necessarily mean lower overall costs if other fees, services, or transaction requirements are not considered. The most useful comparison is based on the complete payment environment, including interchange, processor pricing, equipment, technology, support, and the types of transactions the business processes most frequently. Reviewing actual processing statements can provide a much clearer picture than relying on a headline rate alone.
Understanding interchange can also help business owners have more productive conversations with their payment provider. If processing costs change over time, reviewing transaction types and payment patterns can help identify what is contributing to those changes. Businesses may also be able to improve efficiency by using integrated payment technology, reducing unnecessary manual entry, or selecting solutions that better match the way their customers pay. The goal is not necessarily to eliminate interchange costs, but to understand them and make informed decisions about the overall payment strategy.
At Preserve Payments, we believe businesses should have a clear understanding of what they are paying for and how their payment technology supports their operations. From payment processing and Clover POS to online payments, mobile payments, and reporting, our approach focuses on finding solutions that fit the way each business operates. By looking beyond a single processing rate and considering the complete cost, technology, and support provided, businesses can make more informed payment decisions while protecting their time, margins, and long-term growth.